
TLDR
Labor's 30 per cent minimum tax on discretionary trust distributions carries a compliance cost problem: Wilson Asset Management estimates family businesses will spend $8 billion to $13.3 billion just to adapt, against a five-year revenue forecast of $4.5 billion. With the Coalition opposed and the Greens pressing for a Senate inquiry, passage looks unlikely before late 2026.
A tax that costs more to comply with than it collects
Wilson Asset Management estimates family businesses face a combined bill of $8 billion to $13.3 billion in advice and restructuring costs to comply with the new rules.[1] The government's own five-year revenue forecast for the policy sits at $4.5 billion.[1] That arithmetic is difficult to defend on any reading of sound tax design.
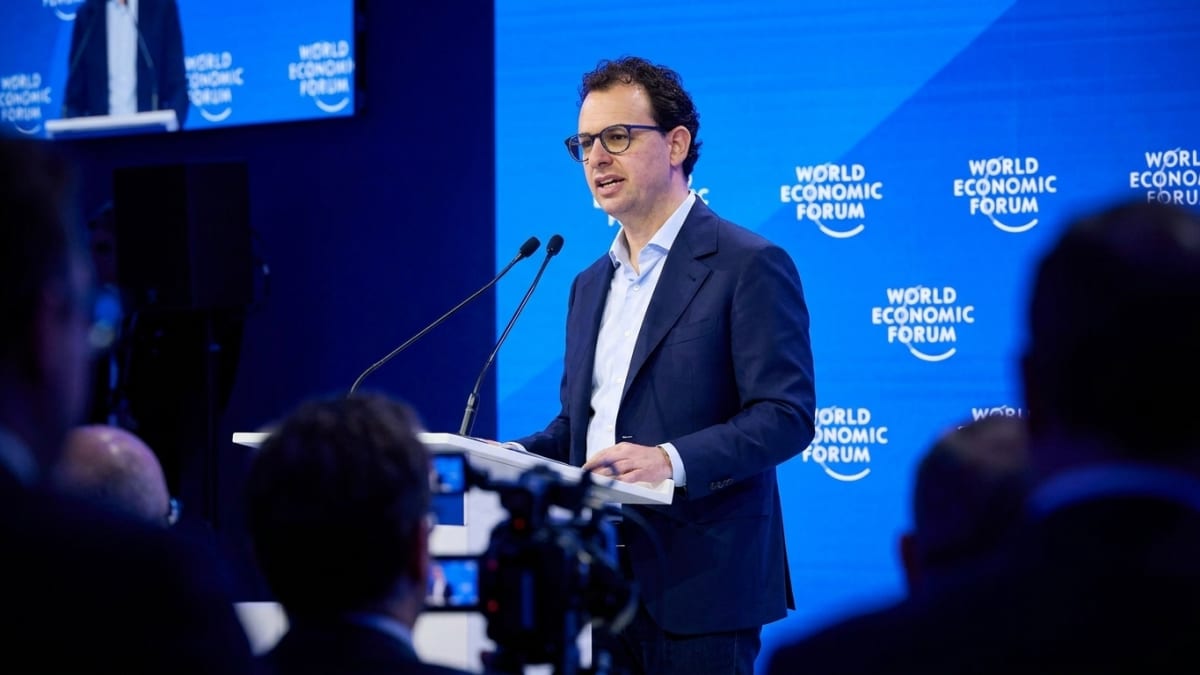
Geoff Wilson, Chairman of Wilson Asset Management, said: "The budget expects the tax to raise $4.5 billion over five years. We are asking small business to spend two to three times that much before a single dollar of it is collected."[1]
The fairness case, examined
Treasurer Jim Chalmers made the equity argument plainly: "We're delivering a fairer tax system and helping fund tax cuts for workers by better aligning the tax rate on trust income with tax rates paid by workers."[2] Wage earners pay marginal rates that trusts can legally sidestep by distributing income to lower-rate beneficiaries, and closing that gap is the stated rationale.
Treasury's own consultation document found that of around 350,000 active small businesses operating through a discretionary trust in 2022-23, roughly 60 per cent, or about 210,000, will face additional tax or restructuring costs under the proposal.[3] These are businesses that use trusts for asset protection and succession planning, structures their accountants set up decades ago.
Treasury's own analysis shows that 40 per cent of the 350,000 small businesses operating through a discretionary trust, around 140,000 firms, are not expected to pay additional tax or restructure at all in any given year.[3] Chalmers has leaned on this to argue the impact is limited, noting fewer than ten per cent of Australia's 2.7 million active small businesses would be affected by these reforms in any given year.[2] The 210,000 businesses still facing restructuring bills remain a substantial cohort by any measure.
Labor has offered rollover and election options to soften the restructuring blow. State stamp duties on asset transfers remain outside federal control, and residual uncertainty over exemptions means many business owners will spend heavily on advice simply to find out whether they need to act at all.
Who is blocking the bill and why it matters
Chalmers is due to introduce the legislation into parliament this week.[4] The Coalition opposes the policy on economic grounds; the Greens are pressing from the other direction for a Senate inquiry and pushing to close an exemption that allows trust distributions to cover private school fees.[4] Two parties pulling in opposite directions makes passage before late 2026 look unlikely.
The Greens' position is that the bill contains a loophole allowing school fees to be paid through trust distributions without triggering the minimum tax, a concession they want removed as the price of support.[4] Labor faces negotiating two incompatible sets of objections at the same time.
KEY TAKEAWAYS
SOURCES & CITATIONS
FREQUENTLY ASKED QUESTIONS
What is the 30 per cent minimum trust tax?
How many businesses are affected?
Why do compliance costs exceed expected revenue?
What is the Greens' objection to the bill?
Important
General financial information only. Not personal financial advice. Consult a licensed financial adviser before making investment decisions.